Entry in What Coverage a New Driver Should Choose
How to Choose a Car Insurance Deductible as a New Driver
Learn how choosing between a $500 and $1,000 deductible affects car insurance premiums for new drivers, and how to pick the right out-of-pocket balance.
By Priya Raman · Editor
Published
Answer in brief
Choosing a car insurance deductible requires balancing upfront premium savings against what you can afford to pay immediately after an incident. While raising a collision or comprehensive deductible reduces annual costs, inexperienced drivers face higher claim frequencies that make higher out-of-pocket risk harder to absorb. Here is how to calculate the optimal deductible for your vehicle and financial situation.
How Deductibles Work on New Driver Auto Policies
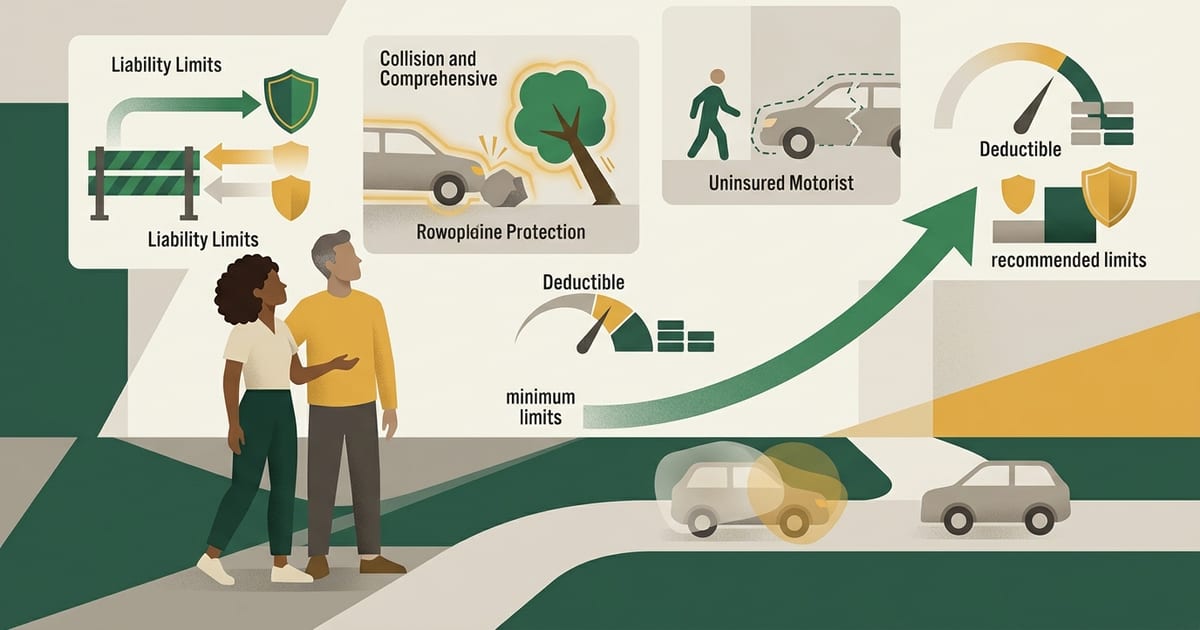
When purchasing car insurance for new drivers, one of the most consequential financial decisions is choosing your deductible. A deductible is the specific amount of money you agree to pay out of pocket toward a covered repair before your insurer pays the remainder of a claim. Deductibles apply exclusively to physical damage coverages—specifically collision coverage and comprehensive coverage. They do not apply to bodily injury liability or property damage liability, which pay for injuries or vehicle damage you cause to others.
For a newly licensed driver, deductibles present a strategic tradeoff. According to the Insurance Information Institute, auto insurance pricing is driven by risk evaluation, where base rates reflect the likelihood of a claim. Setting a higher deductible transfers more immediate financial responsibility to the policyholder, which lowers the ongoing premium. Setting a lower deductible provides peace of mind if an accident occurs, but results in higher recurring bills every month. For families managing how much car insurance costs, selecting the correct dollar figure is essential to balancing monthly cash flow against unexpected repair bills.
Evaluating the Math: $500 vs. $1,000 Deductible
Data from the Insurance Information Institute indicates that increasing your deductible from $200 to $500 can reduce your collision and comprehensive premium by 15% to 30%. Taking that deductible from $500 up to $1,000 can reduce physical damage costs by 40% or more. Because inexperienced operators face higher baseline rates due to statistical risk, these percentage reductions translate into substantial dollar savings.
However, newly licensed motorists must evaluate whether those upfront savings justify the added exposure. Research from the Insurance Institute for Highway Safety indicates that the fatal crash rate per mile driven for drivers aged 16 to 19 is just over three times the rate for drivers aged 20 and older, with the all-severity crash rate being more than four times higher. Because beginners are statistically more likely to experience a minor scrape, parking mishap, or collision during their first years on the road, the probability of having to pay that deductible is noticeably elevated.
If selecting a $1,000 deductible saves an illustrative $300 annually on comprehensive and collision coverage, you must avoid a claim for more than three years to break even on the additional $500 out-of-pocket risk. If an accident occurs within the first 12 months, paying that higher deductible wipes out any accrued savings immediately.
The 10-Times Vehicle Value Rule
When deciding on deductibles and physical damage coverage, you should always evaluate the market value of the car being driven. The Insurance Information Institute recommends examining whether carrying collision and comprehensive coverage makes financial sense on older vehicles. A common rule of thumb is that if the annual cost of comprehensive and collision coverage exceeds 10% of the car's actual cash value, dropping physical damage entirely should be considered.
When selecting the best cars for new drivers to insure, driving an older sedan worth an estimated $3,000 might mean paying $1,200 annually for physical damage coverage with a $1,000 deductible. In the event of a total loss, the maximum payout after the deductible would be roughly $2,000. In such scenarios, eliminating collision and comprehensive entirely or keeping a lower deductible while preparing to replace the vehicle through personal savings may be more practical.
Steps to Choose the Right Deductible
- 1
Audit Your Liquid Emergency Savings
Never agree to a deductible you cannot pay immediately. Ensure that $500 or $1,000 is readily accessible in a dedicated savings account before selecting that tier on your policy.
- 2
Request Side-by-Side Premium Quotes
Ask the insurer or use a comparison platform to price identical coverage at $250, $500, and $1,000 deductible levels to calculate the exact dollar difference for your specific vehicle.
- 3
Calculate the Break-Even Timeline
Divide the deductible difference (for example, the $500 increase between a $500 and $1,000 level) by your annual premium savings to determine how many claim-free years are required to make the risk worthwhile.
- 4
Verify Driver Experience and Mileage
If the beginner driver commutes long distances or drives in heavy urban traffic, a lower deductible provides safer budgeting stability against elevated crash probability.
- 5
Re-evaluate When Rates Begin to Drop
As inexperienced drivers build a clean record and how rates drop takes effect over two to three years, reconsider raising deductibles to capture additional premium discounts.
Comprehensive vs. Collision Deductibles
Many insurance policies allow drivers to select different deductible amounts for comprehensive and collision coverages. Collision coverage pays when your car strikes another vehicle, a stationary object, or rolls over. Comprehensive coverage pays for damage caused by perils outside your control, such as theft, vandalism, hail, fire, or animal strikes.
Because comprehensive claims occur less frequently and generally carry a smaller premium portion than collision, many policyholders choose a lower deductible for comprehensive (such as $250 or $500) while choosing a higher deductible for collision (such as $1,000). This keeps out-of-pocket costs low for unpredictable incidents like a cracked windshield or weather damage while lowering the larger collision premium.
Questions & answers
What happens if I cannot afford my deductible after an accident?
The repair shop typically requires payment of your deductible before releasing your vehicle. If you cannot pay, the vehicle remains at the repair facility, and you may incur daily storage fees. Always choose a deductible you can afford from liquid savings.
Do I pay a deductible if an accident was not my fault?
If another driver is at fault and their insurer accepts liability, their property damage liability coverage pays for your repairs without a deductible. If you use your own collision coverage to repair the car faster, you pay your deductible, but your insurer will attempt to recover it through subrogation.
Can a new driver have different deductibles on different cars?
Yes. If you have multiple vehicles on a policy, each vehicle can carry distinct collision and comprehensive deductibles tailored to each car's cash value and primary driver.
Does a higher deductible affect liability coverage?
No. Deductibles apply strictly to collision and comprehensive physical damage coverages. Bodily injury and property damage liability coverages carry no deductibles.
Terms: Deductible, Collision coverage, Comprehensive coverage, Premium, Clean record
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Teenagers — Insurance Institute for Highway SafetyIndependent researchTeen crash risk, graduated driver licensing research and vehicle recommendations for young drivers.
- Graduated licensing laws by state — Insurance Institute for Highway SafetyIndependent researchState-by-state learner, intermediate and full-licence ages, night-driving and passenger restrictions.
- 2019–2023 Auto Insurance Database: average premium supplement — National Association of Insurance Commissioners (2025)Statistical dataCountrywide average expenditure $1,281 in 2023 (+13.98%); combined average premium $1,438; state tables for liability, collision and comprehensive.
- Fatality facts: Teenagers — Insurance Institute for Highway Safety (2024)Statistical dataFatal crash rate per mile driven for 16–19-year-olds is just over 3 times the rate for drivers 20 and older (2022 travel data); all-severity crash rate is over 4 times; risk is highest at 16–17.
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
- What is covered by a basic auto insurance policy? — Insurance Information InstituteConsumer guidanceDefines bodily injury and property damage liability, MedPay, PIP, uninsured/underinsured motorist, collision, comprehensive and glass coverage.
- How much auto coverage do I need? — Insurance Information InstituteConsumer guidanceWhy state minimums are a floor; choosing liability limits that protect assets; when collision and comprehensive are worth keeping.
- Auto insurance for teen drivers — Insurance Information InstituteConsumer guidanceAdding a teen to a parent's policy versus a separate policy; good-student and driver-training discounts; vehicle choice.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.
Entry
Why New Drivers Need Uninsured Motorist Coverage
Learn why uninsured motorist protection is critical for new drivers, how state uninsured rates affect risk, and how to select proper policy limits.
Parent guide
What Coverage a New Driver Should Choose
Liability limits, collision and comprehensive, uninsured motorist and deductibles for a first policy—what matters, what is optional, and why minimum limits are a poor fit for new drivers.